Wealth Advisors in Houston for the Decisions You Only Make Once
You’ve spent decades building your savings, and now the big decisions are arriving together: when to stop working, which pension option to elect, and what to do with the company stock in your 401(k).
From our Memorial Drive office in Houston, our wealth advisors help families near or in retirement bring their investments, retirement income, taxes, and estate plans together in one plan. We work directly with your CPA and estate attorney, so you aren’t stuck passing messages between them.
- See how each decision connects
- Plan ahead of the deadlines
- Work with advisors you know by name
Working With a Wealth Advisor in Houston, TX
The pension packet arrives in the spring, the company stock statement shows a position that’s grown bigger than you intended, and somebody in HR mentions an early retirement window. A milestone you’ve pictured for years suddenly has to become a real date on a calendar.
For a lot of Houston professionals in their late 50s and 60s, these decisions come at the same time, and most of them only happen once. That’s usually the point when someone starts looking for a wealth advisor.
You’ve managed your own money well enough to get here. What changed is the sheer number of one-time, hard-to-undo choices now facing you all at once, and the worry behind them: that you’ll find out you got one wrong 10 years after you could have fixed it.
By the end of this page, you should be able to tell whether you need a wealth advisor at all, and what to ask the ones you talk to.
What Does a Wealth Advisor Do?
A wealth advisor coordinates your investments, retirement income, taxes, and estate plans as one connected plan rather than managing a portfolio on its own. Picking holdings is a small part of it. Most of the work is confirming each decision accounts for the others it affects.
Say you’re weighing a Roth conversion in the first years after you stop working, when your taxable income is lower than it’s been in decades. A Roth conversion moves money from a traditional retirement account into a Roth IRA, and the pre-tax portion counts as taxable income in the year you do it.
Treated as a tax question on its own, the answer is whatever keeps this year’s bill lowest. Put the same decision inside a retirement plan and it also moves your Medicare premiums two years out, the size of your required withdrawals in your 70s, and what your children inherit. It decides what your spouse would pay at single-filer rates if you go first, often as soon as the year after. That’s what people tend to avoid asking until it’s too late to change.
That coordination covers retirement planning, investment management, financial planning, and legacy and estate planning, handled by people who talk to each other about your file instead of four professionals who each see only one piece of it.
Wealth Advisor, Financial Advisor, or Wealth Management Advisor?
None of these titles is defined in securities law the way “investment advisor” is, and they don’t tell you how someone is registered or paid. Two advisors carrying the same title can do completely different work at two firms a mile apart, so what you ask matters far more than what’s printed on the card.
So here’s what to ask.
What does the relationship cover?
Some advisors manage a portfolio and stop there. Others handle income planning, tax coordination, and estate questions inside the same engagement. Ask them to list everything included in their fee, and (more importantly) what isn’t.
How are you paid?
Fees, commissions, or some combination. Get the answer in plain dollars, not only percentages.
Who will I be talking to?
The person who explains the relationship isn’t always the person who services it. Ask who will actually be managing your account and answering your calls after you sign on.
We would rather you put these to us than take our word for anything. Our guide to choosing a financial advisor in Houston covers how to compare firms against criteria you set yourself, and our full list of questions to ask a financial advisor gives you the rest of the interview.
Signs it May Be Time to Work With a Wealth Management Advisor
- A pension lump sum or annuity election. You pick one, and that’s it. Which one fits depends on your other income sources, your health, your spouse’s situation, and what the rest of your portfolio has to do. Whether you have the choice at all depends on when you were hired, since several Houston employers have closed their pension plans to newer staff while long-tenured employees still have it. We keep retirement resources for employees of BP and Shell.
- Company stock within your 401(k). If your plan holds employer stock that’s grown substantially, a rule called net unrealized appreciation may let you move that stock out and pay long-term capital gains rates on the growth instead of ordinary income rates. The conditions are strict, and a routine rollover can close the door by accident. Company stock makes up a large share of the savings plans at several Houston employers (ExxonMobil and Chevron are among them).
- Deferred compensation elections. Many of these are filed years before the payout and can’t be changed afterward. If you get the timing wrong against your retirement year, the money lands in the worst year it could have. These plans are usually open only to more senior staff. See our retirement resources for ConocoPhillips and Phillips 66 employees.
- A severance or early retirement package with a deadline on it. These arrive with a decision window measured in weeks. What that number is worth to you depends on which tax year it falls in and how it aligns with the retirement income plan you were already building.
- The years between your last paycheck and your first required withdrawal. We call this stretch the tax valley. Required minimum distributions (the withdrawals the IRS makes you take from traditional pre-tax retirement accounts once you reach a certain age) haven’t started yet, so your taxable income is temporarily low. The bracket space in those years is “use it or lose it,” and planning around RMDs before they begin can change your tax bill for the rest of your retirement.
- An estate plan you haven’t opened in 10 years. Beneficiary designations on your accounts outrank your will. If those forms still name an ex-spouse, a parent who has died, or your estate rather than a person, the documents your attorney drafted may not control where the money ends up.
What Is the Certified Private Wealth Advisor® Designation?
The Certified Private Wealth Advisor®, or CPWA®, designation means an advisor has completed an advanced certification built for working with high-net-worth clients. The Investments & Wealth Institute awards it, and the coursework concentrates on the tax, estate, and transition questions that tend to surface at higher asset levels.
Earning it takes a qualifying degree or credential, five years in financial services, an executive education program through a registered provider such as Chicago Booth or Yale, and a proctored exam. FINRA keeps a public listing of the designation.
On our team, Angela K. Wascom-Gantt, CIMA®, CPWA®, holds the designation.
A credential tells you what someone has studied, which is useful but partial. It won’t tell you whether they’ve ever read your employer’s plan document. Before you hire anyone, including us, look the firm up on FINRA BrokerCheck.
How Our Wealth Advisors Work With Houston Families
Based on Memorial Drive, we are a fee-based advisory firm working primarily with families near or in retirement. Because many of our clients spent their careers in the energy sector, we bring deep experience with the specific plan documents, stock options, and retirement choices unique to major Houston employers.
Our work begins with a simple three-step process: we sit down to listen to your goals, design a custom strategy around what you want this next stage to look like, and only put your plan into motion once you’ve reviewed every detail.
That plan is powered by our Dynamic A.G.E. Approach (Adjust, Grow, Ensure). It is designed to create a reliable retirement paycheck once your regular salary ends, protect your purchasing power against inflation, and adapt as your life evolves.
As a lean team by design, we offer a personal, transparent relationship. You’ll always know who you’re talking to, and your assets remain protected with an independent third-party custodian where you can log in and view your accounts anytime. We also collaborate directly with your CPA and estate attorney so you don’t have to act as the middleman between your advisors.
Whether you’re located across Memorial, the Energy Corridor, Katy, and The Woodlands, or have moved outside of Texas, we serve families locally and nationally via secure video conferencing.
Meet Our Wealth Advisors

Robert G. Gilliland, CRPC®
Founder, Managing Director and Senior Wealth Advisor: More than three decades advising clients, including over 10 years as a Resident Director at Merrill Lynch before he founded the firm
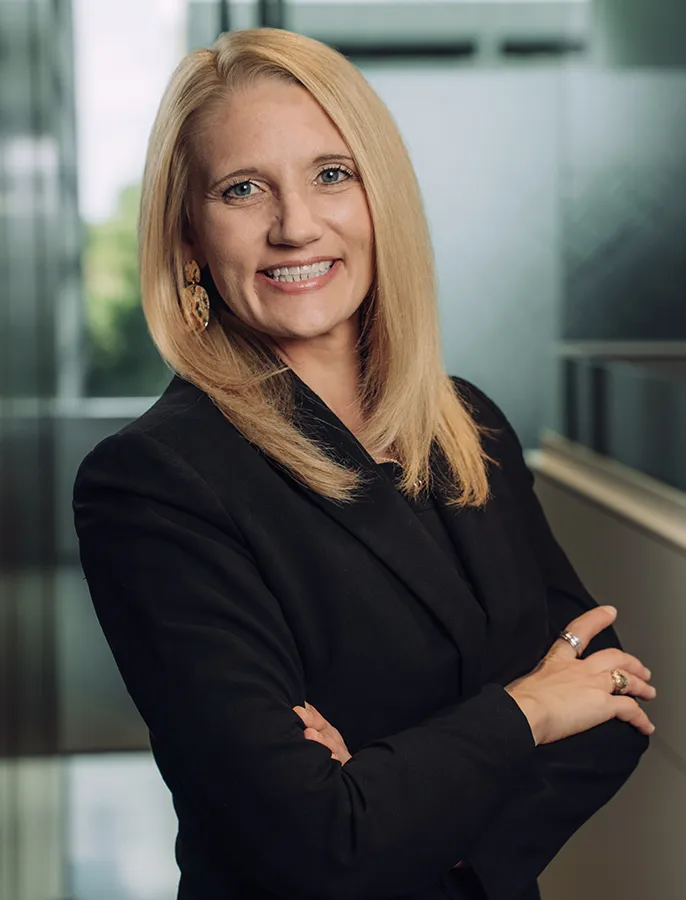
Karen E. Heider, CRPC®, CDFA®, BFA™
Senior Wealth Advisor: Over a decade in financial planning, focused on retirement, exit planning, and divorce financial analysis
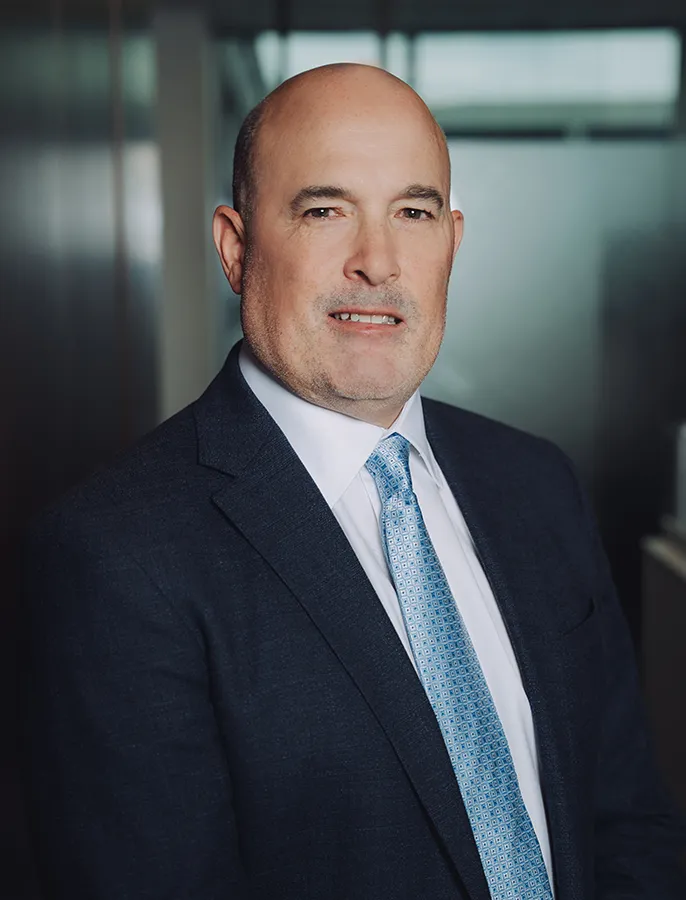
Christopher C. Davis, MBA, CEPA®
Managing Director and Senior Wealth Advisor: Twenty-plus years in wealth management and capital markets, working mostly with business owners and multi-generational families
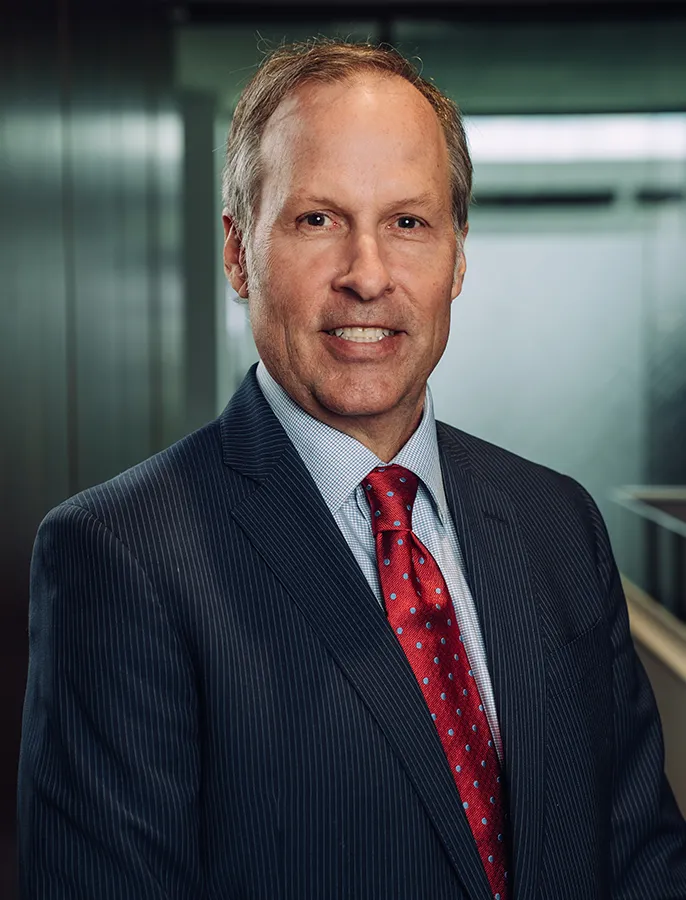
Mike W. Alexander, CIMA®
Chief Investment Officer and Wealth Manager: More than 30 years in portfolio design, previously Director of Multi-Asset Strategies and Solutions at BlackRock
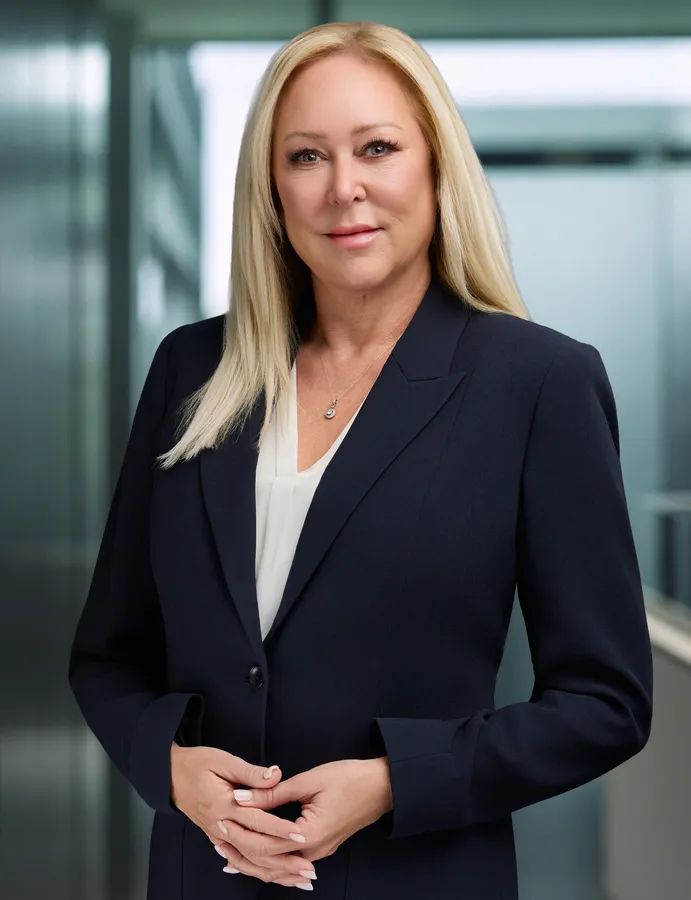
Angela K. Wascom-Gantt, CIMA®, CPWA®
Financial Advisor: Thirty-plus years in financial services, focused on investment management and retirement income planning
The full team page introduces everyone who works on client plans.
Frequently Asked Questions
What does a wealth advisor do?
Is a wealth advisor the same as a financial planner?
How much do I need to work with a wealth advisor?
Firms set their own thresholds and they vary widely, so there’s no industry-wide number. The more useful question is whether the complexity of your situation justifies the cost of the advice. Someone facing a pension election, concentrated company stock, and a retirement date within the next three years often has more at stake than the balance alone would suggest. Our article on how much money you need to hire a wealth manager covers this in more depth.